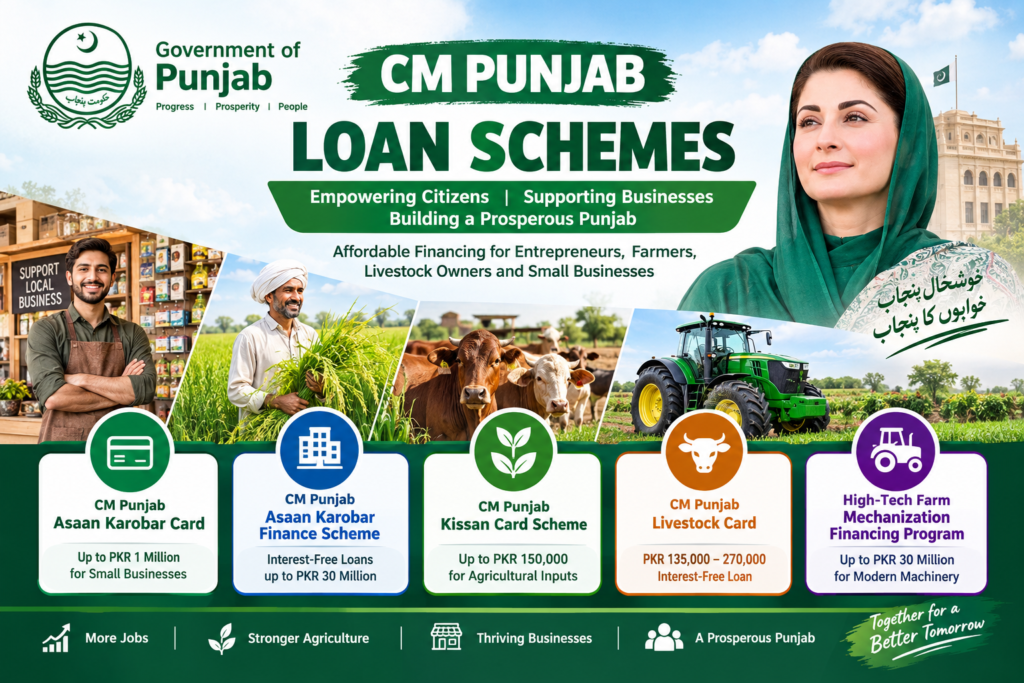
The Government of Punjab has introduced several loan and financing schemes to support entrepreneurs, farmers, small businesses, livestock owners, and other eligible citizens across the province. These initiatives are designed to provide access to affordable or interest-free financing for business development, agriculture, livestock, and other productive activities.
Among the major initiatives are the CM Punjab Asaan Karobar Card, CM Punjab Asaan Karobar Finance Scheme, CM Punjab Kissan Card, CM Punjab Livestock Card, and High-Tech Farm Mechanization Financing Program. Each scheme has its own eligibility requirements, financing limits, repayment structure, and intended beneficiaries.
This article explains the major CM Punjab loan schemes 2026, their key features, eligibility requirements, loan amounts, repayment terms, and how applicants can check the official information before applying.
What Are CM Punjab Loan Schemes?
CM Punjab loan schemes are government-supported financing initiatives introduced by the Punjab Government to facilitate economic activity and provide financing opportunities to eligible residents.
Instead of relying entirely on conventional commercial loans, eligible applicants may access specially designed financing for activities such as starting a business, expanding an existing enterprise, purchasing agricultural inputs, supporting livestock activities, or investing in modern agricultural machinery.
The schemes are targeted at different groups, so applicants should select the program that matches their purpose.
1. CM Punjab Asaan Karobar Card
The CM Punjab Asaan Karobar Card is designed to provide financing support to small businesses and entrepreneurs in Punjab.
According to the Punjab Government, the scheme provides a revolving credit facility with a maximum limit of PKR 1 million. The financing is intended for business-related expenses and can be used for activities including vendor and supplier payments, utility bills, government fees, taxes, and certain business-related cash requirements.
The official information lists a three-year tenure, with repayment structured after the initial period. The card also allows digital transactions through POS and mobile applications.
Key Features
- Maximum financing: Up to PKR 1 million
- Tenure: 3 years
- Revolving credit facility
- Grace period available under the scheme
- Business-related digital payments
- Supplier and vendor payments
- Utility bills and government payments
- Limited cash withdrawal facility for eligible business purposes
The scheme can be particularly relevant for small entrepreneurs who need working capital rather than a large long-term business loan.
The Punjab Small Industries Corporation information states that applicants should generally be 21 years or older and up to 57 years, hold a valid CNIC, be residents of Punjab, and have a business or proposed business in Punjab.
Applicants should always verify the latest requirements on the official government portal before submitting an application.
2. CM Punjab Asaan Karobar Finance Scheme
The CM Punjab Asaan Karobar Finance Scheme is intended for small and medium-sized enterprises and entrepreneurs who require larger amounts of financing.
The official Punjab Government describes the program as providing interest-free loans to support new businesses as well as existing businesses that want to expand, modernize operations, or obtain working capital.
The scheme can support activities such as:
- Starting a new business
- Expanding an existing business
- Modernization and balancing, modernization and replacement
- Working capital
- Commercial logistics
- Climate-friendly and resource-efficient technologies
- Agriculture-related SMEs
According to the Punjab Small Industries Corporation’s published information, the financing structure includes two tiers.
Tier 1
Tier 1 provides financing from PKR 1 million to PKR 5 million and is described as a clean loan supported by personal guarantees.
Tier 2
Tier 2 provides financing from PKR 5 million to PKR 30 million and is a secured financing facility.
The published eligibility criteria include an age range of 25 to 55 years, a valid CNIC, a valid NTN, and a clean ECIB/credit history. Applicants must also have appropriate business premises for relevant categories of financing.
Repayment can extend for up to five years, with grace periods depending on whether the business is new or already operating.
3. CM Punjab Kissan Card Scheme
Agriculture is one of Punjab’s most important economic sectors, and the CM Punjab Kissan Card Scheme has been introduced to provide farmers with financing for agricultural inputs.
According to the official Punjab Government portal, eligible farmers can receive financing of up to PKR 150,000 per season for five acres, calculated at PKR 30,000 per acre. The financing is specifically intended for agricultural inputs such as fertilizer and seed.
The official scheme information states that farmers holding up to 12.5 acres may be eligible, subject to the applicable requirements. A mobile SIM registered against the farmer’s own CNIC is also among the stated requirements.
Important Features
- Financing for agricultural inputs
- Maximum stated financing of PKR 150,000 per farmer per season
- Coverage based on eligible acreage
- Intended for items such as fertilizer and seed
- Farmer verification through official systems
The Kissan Card is therefore different from a general-purpose personal loan. Its financing is linked to agricultural production and eligible agricultural inputs.
Farmers should check the latest Agriculture Department instructions before applying because eligibility conditions, registration procedures, and program details can be updated.
4. CM Punjab Livestock Card
The CM Punjab Livestock Card is another financing initiative aimed at supporting farmers involved in livestock activities.
The Punjab Government states that eligible farmers can receive interest-free loans ranging from PKR 135,000 to PKR 270,000. The financing period is four months, with an additional one-month grace period for repayment.
The program is designed to provide financial support for livestock-related requirements and is intended to help eligible farmers manage their livestock operations.
Key Features
- Loan range: PKR 135,000 to PKR 270,000
- Interest-free financing
- Four-month loan period
- One-month additional grace period
- Targeted toward eligible livestock farmers
The official Punjab Livestock Department also provides information and a helpline for livestock-related government initiatives.
5. CM Punjab High-Tech Farm Mechanization Financing Program
For farmers, agricultural service providers, and entrepreneurs interested in modern machinery, the Punjab Government has introduced the High-Tech Farm Mechanization Financing Program.
This program offers interest-free financing of up to PKR 30 million for eligible high-tech agricultural machinery. According to the Punjab Government, the program is designed to improve agricultural productivity, reduce dependence on manual labor, and address losses associated with delayed or inefficient harvesting, threshing, and handling.
The published program details include:
- Maximum loan: PKR 30 million
- Minimum applicant equity: 20%
- Age range: 21–65 years
- Interest-free financing through the Bank of Punjab
- Repayment period: 5 years
- Repayment: 20 equal quarterly installments
- Grace period: 6 months
- Processing fee: PKR 5,000
The program covers selected high-tech agricultural machinery and can be relevant to farmers and agricultural businesses looking to modernize their operations.
Who Can Apply for CM Punjab Loan Schemes?
Eligibility depends on the specific scheme.
For example, a small business owner may be more suited to the Asaan Karobar Card, while an SME requiring several million rupees may consider Asaan Karobar Finance. A farmer purchasing agricultural inputs may look toward the Kissan Card, while an eligible livestock farmer may benefit from the Livestock Card.
Common requirements across different programs can include:
- Valid Pakistani CNIC
- Punjab residency
- Appropriate age requirement
- Relevant business, agricultural, or livestock activity
- Registered mobile number in the applicant’s name where required
- Clean credit history for applicable business financing
- NTN or business documentation for certain financing programs
- Additional documents depending on the scheme
Applicants should not assume that meeting the requirements of one program automatically makes them eligible for another.
How to Apply for CM Punjab Loan Schemes
The application process varies from one program to another. Applicants should use official Punjab Government portals and designated institutions rather than relying on unofficial agents or social-media advertisements.
For business financing, applicants may need to provide CNIC information, business details, tax information, premises information, financial details, and other documents required by the program.
For agriculture-related programs, farmers may need to complete verification through the Agriculture Department and meet landholding or other eligibility requirements.
Before submitting an application, applicants should carefully check:
- Eligibility requirements
- Maximum financing amount
- Required documents
- Repayment schedule
- Processing charges, if applicable
- Eligible uses of the financing
- Application deadlines, if any
- Official application portal
The Punjab Government’s official website provides information about these initiatives and should be treated as the primary source for updated program details.
Important Advice for Applicants
Government financing can provide an opportunity to start or expand a productive activity, but applicants should understand the repayment obligations before accepting financing.
A loan should not be treated as free money. Even where the government provides interest-free financing, the principal amount generally still has to be repaid according to the applicable schedule.
Applicants should prepare a realistic business plan or spending plan before applying. For example, a person seeking business financing should estimate expected monthly revenue, operating expenses, inventory requirements, employee costs, utilities, taxes, and loan repayments.
Farmers should similarly calculate expected crop or livestock income before taking financing.
Applicants should also avoid paying unauthorized individuals who claim they can guarantee approval. Information should be verified through official government websites and helplines.
The Punjab Government’s official helpline page currently lists 1786 for Asaan Karobar and 0800-17000 for Agriculture-related assistance.
Final Thoughts
The CM Punjab loan and financing programs cover several different economic needs. The Asaan Karobar Card focuses on smaller business financing, while Asaan Karobar Finance is designed for larger SME requirements. The Kissan Card supports eligible farmers with agricultural inputs, while the Livestock Card provides financing for eligible livestock farmers. Meanwhile, the High-Tech Farm Mechanization Financing Program targets investment in modern agricultural machinery.
Because eligibility criteria and program rules can change, applicants should always verify the latest information through official Punjab Government portals before applying.
ywkwnqhwmunueepwqgrzziovimhykq